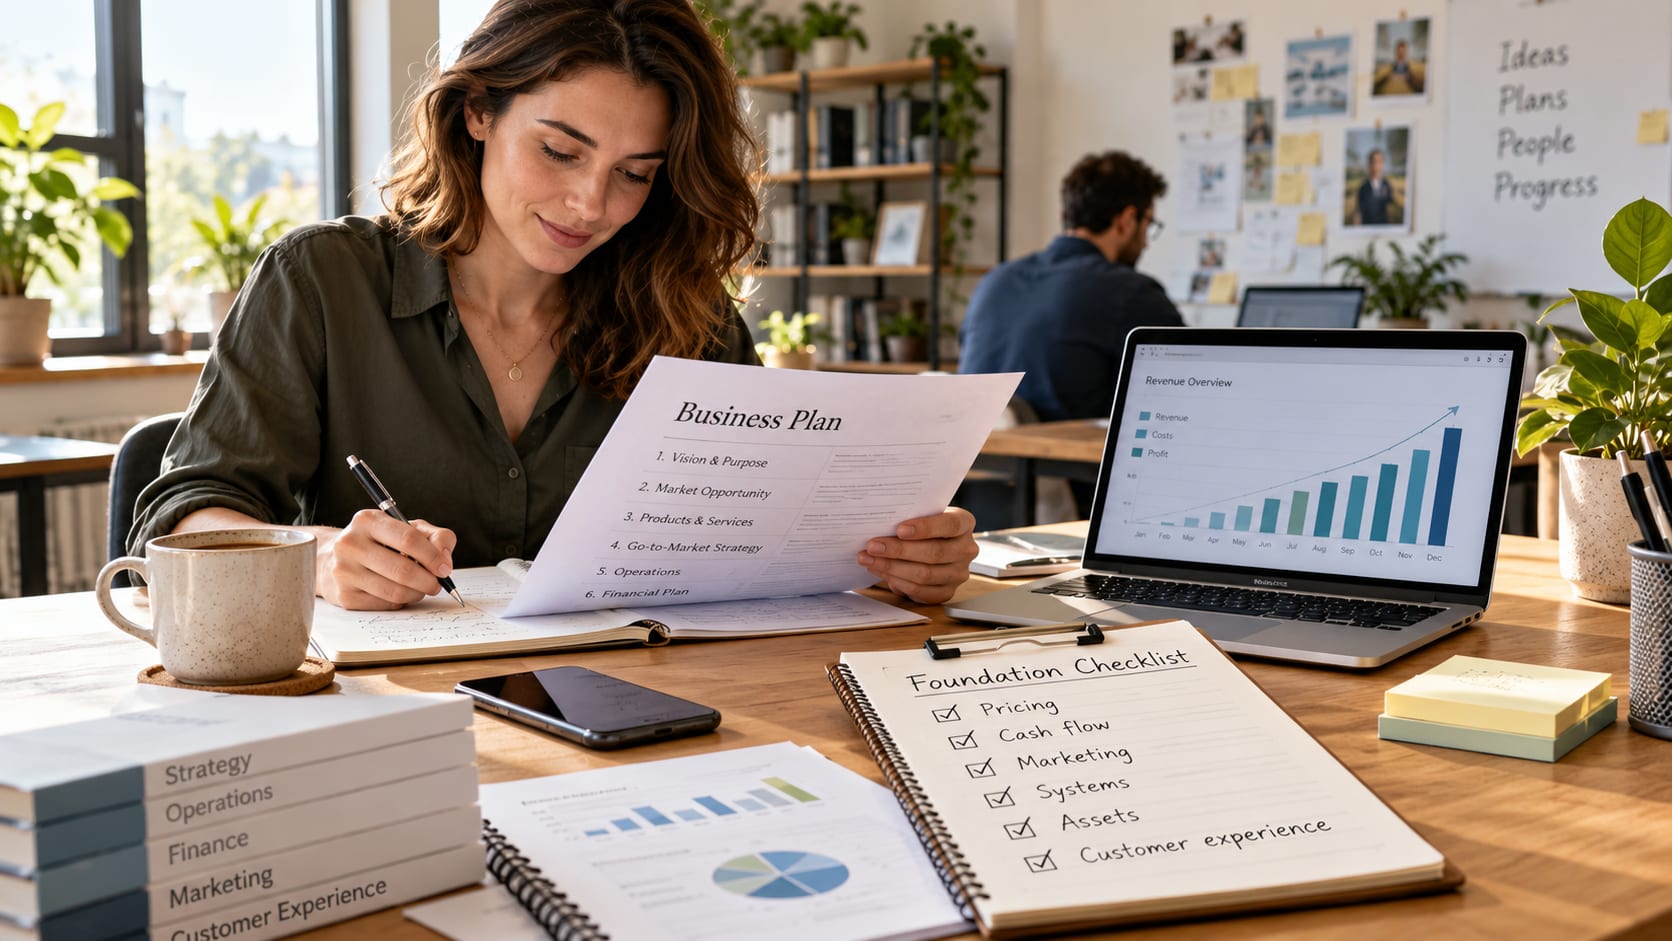
Starting a new business? Get the foundations right with practical advice on pricing, cash flow, marketing, fixed assets, systems and customer experience.
Starting a business is often presented as an exercise in momentum.
Launch quickly. Find customers. Make sales. Grow.
There is some truth in that. Businesses do not survive because their founders spend six months perfecting a filing system.
But speed can become expensive when the basics are wrong.
Poor pricing becomes harder to fix once customers expect it. Messy finances become more painful when transaction volumes increase. Weak processes that are manageable with two employees can become chaotic with twenty. Even small mistakes tend to become larger as the business grows around them.
The best time to build good foundations is therefore usually before they feel necessary.
You do not need a perfect company from day one. You do need a business that can become bigger without becoming increasingly difficult to control.
Understand What You Are Actually Selling
This sounds obvious, yet many new businesses describe what they sell far more clearly than they understand why somebody would buy it.
A plumber sells plumbing services. A software company sells software. A courier delivers parcels.
That is only half the answer.
Customers are usually buying a result: fewer problems, less risk, more convenience, better performance, faster delivery or a saving of time.
That distinction matters because it affects everything from pricing to marketing.
If you cannot explain why somebody should choose your business instead of a competitor in one or two clear sentences, the problem is worth solving early.
A good proposition does not need to be revolutionary. It needs to be specific enough that the right customer recognises themselves in it.
Get Pricing Right Before Volume Hides The Problem
Revenue can disguise an unhealthy business for longer than many owners expect.
A company can be busy, growing and taking more money every month while still making surprisingly little profit.
New businesses often price too low because they want customers quickly. That can work temporarily, but low prices are difficult to unwind once they become established.
Make sure your pricing reflects the real cost of providing the product or service.
That means including the obvious expenses, but also the less visible ones: administration, insurance, software, travel, returns, time spent quoting, equipment replacement and the inevitable jobs that take longer than expected.
A £1,000 sale is not particularly impressive if it costs £950 to deliver.
Understanding margin early gives you room to make sensible decisions later.
Keep Control Of Cash
Profit and cash are related, but they are not the same thing.
A business can be profitable on paper and still struggle to pay its bills if customers pay slowly or too much money is tied up elsewhere.
Cash flow deserves attention from the beginning.
Know what is coming in, what is going out and when large payments are due. Invoice promptly. Chase overdue balances rather than letting them quietly accumulate. Keep enough of a buffer that one unexpected bill does not become a crisis.
It is also worth separating business and personal finances immediately.
The more disciplined the financial side is at the beginning, the easier it becomes to understand what is actually happening when the business grows.
Treat Valuable Fixed Assets Properly
Some businesses can start with little more than a laptop.
Others need vehicles, machinery, specialist equipment, computers, warehouse systems or other valuable assets before they can make their first sale.
Those purchases need more thought than ordinary day-to-day expenses.
Fixed assets can have useful lives spanning several years. They may depreciate, require maintenance, move between locations, be upgraded or eventually sold. Once a company owns enough valuable equipment, keeping an accurate record becomes increasingly important.
A simple spreadsheet may be perfectly adequate for a small business with a handful of assets.
But if those assets become valuable, numerous or complicated, specialist fixed asset help may be worth considering.
That might mean advice from an accountant, better asset-management processes or dedicated fixed asset software capable of tracking depreciation, disposals, locations and asset histories. Whats hard, is finding the pivot point, because ideally you want to go from excel to software before you actually need the software. Sounds odd, but it'll save a huge headache. So, if you feel your business growing, your assets increasing and getting harder to manage, then you need to look into software. For example FinQuery Fixed Assets software page can explain what you need, and you can probably gauge when you'll need it.
The point is not to overcomplicate things when the business is small.
It is to recognise when an informal system has stopped being reliable.
Losing track of a £40 office chair is annoying. Losing track of a fleet of vehicles, expensive machinery or a large quantity of IT equipment is a financial-control problem.
Build Marketing Before You Desperately Need Customers
Marketing is often treated as something a new business should do once everything else is ready.
That is backwards.
A business without a reliable way of attracting customers is permanently vulnerable.
The exact marketing channels will depend on the company. A local service business may rely heavily on search, reviews and referrals. A B2B company might need outbound sales, industry relationships and useful content. An ecommerce brand may depend much more heavily on paid advertising, email and social media.
The important thing is consistency.
Marketing tends to work better when it becomes a system rather than a panic response to an empty sales pipeline.
Start collecting reviews early. Build a useful website. Learn which enquiries turn into good customers. Keep track of where leads come from. Create genuinely helpful content if people research your service before buying.
Most importantly, avoid trying to be everywhere.
Doing two marketing channels properly is usually more valuable than having neglected accounts on eight different platforms.
Physical also helps. Market your business on things that people love to use and/or have. Like customizable promotional products you can give away at events, trade shows or even just in the street.
Create Processes While You Can Still Remember Them
When the founder does everything, processes often live entirely inside the founder's head.
That works until somebody else needs to do the job.
If you repeatedly perform the same task, begin documenting how it should be done.
It does not need to become a 50-page operations manual.
A simple checklist can be enough.
How is a new customer onboarded? What happens when a complaint arrives? Who approves a purchase? Where should important files be stored? What needs to happen when an employee joins?
Documenting these things early makes delegation far easier.
It also forces you to notice inefficient steps while they are still relatively easy to change.
Choose Systems That Can Grow With You
Cheap and simple tools are often exactly what a new business needs.
The mistake is choosing them without thinking about what happens next.
If customer details are stored in one spreadsheet, orders in another and invoices somewhere else, the arrangement may work initially. But once sales increase, the amount of manual work required to keep everything aligned increases too.
Try to choose systems that are appropriate today without creating an obvious dead end tomorrow.
That does not mean buying enterprise software for a company with three customers.
It means asking sensible questions about integrations, reporting, user access and what happens when transaction volumes increase.
Good systems should remove administrative work as the business grows, not create more of it.
Protect The Customer Experience
Growth tends to expose weaknesses in customer service.
When there are only ten customers, the owner can personally solve almost every problem.
At one hundred or one thousand, that becomes impossible.
Set expectations clearly from the beginning.
Respond when you say you will. Make pricing understandable. Tell customers what happens next. Deal with complaints properly. Do not promise things simply because saying no feels uncomfortable.
Customers are surprisingly forgiving when something goes wrong and the business handles it well.
They are much less forgiving when they feel ignored.
A strong reputation is one of the few assets a young business can build without a large capital budget.
Build Something That Becomes Easier To Run
The early stage of a business will always involve a certain amount of improvisation.
That is normal.
What matters is whether those temporary solutions gradually turn into proper systems.
Pricing should become more accurate. Financial visibility should improve. Valuable fixed assets should be controlled properly. Marketing should generate demand consistently. Repetitive work should become documented and easier to delegate.
The aim is not bureaucracy.
It is the opposite.
A well-run business should become easier to understand as it grows, not increasingly dependent on the founder remembering everything.
Getting the foundations right will not guarantee success.
But when opportunities arrive, customers increase and the workload becomes heavier, good foundations give the business something extremely valuable:
the ability to grow without losing control.
Comments
Loading comments…